
“Indirect Tax I Indirect Tax Litigation I Customs & FTP I Central Licensing I Arbitration I Advisory”
Dated: 25.09.2026
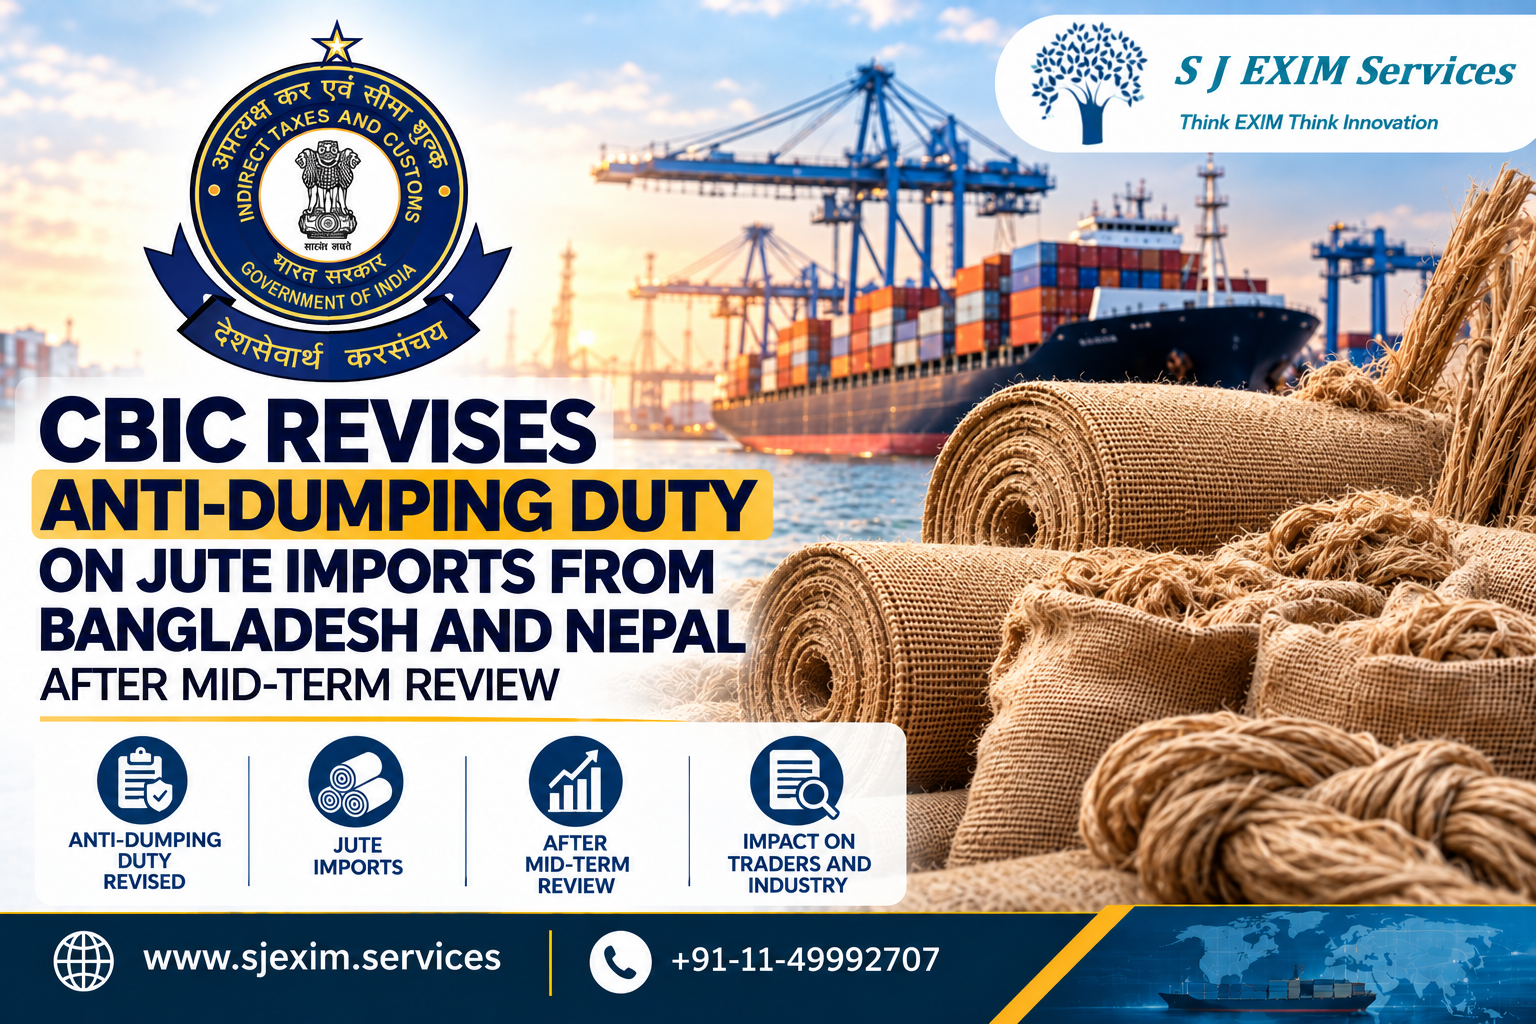
CBIC Revises Anti-Dumping Duty on Jute Imports from Bangladesh and Nepal After Mid-Term Review
The Ministry of Finance, Department of Revenue, has revised the anti-dumping duty (ADD) applicable to specified jute products originating in or exported from Bangladesh and Nepal, following a mid-term review conducted by the Directorate General of Trade Remedies (DGTR).
The revised duty structure has been notified through Notification No. 24/2026-Customs (ADD), dated 24 September 2026 [G.S.R. 845(E)], which amends the earlier Notification No. 33/2022-Customs (ADD), dated 30 December 2022.
The products covered include jute yarn/twine, hessian fabric, jute sacking bags and jute sacking cloth, falling under tariff headings 5307, 5310, 5607 and 6305 of the First Schedule to the Customs Tariff Act, 1975.
Background: DGTR Mid-Term Review
- The existing anti-dumping duty on the subject jute goods was imposed under Notification No. 33/2022-Customs (ADD) dated 30 December 2022.
- The DGTR subsequently initiated a mid-term review through Initiation Notification No. 7/11/2024-DGTR dated 30 June 2025, under Section 9A(5) of the Customs Tariff Act, 1975 read with Rule 23 of the Customs Tariff (Identification, Assessment and Collection of Anti-Dumping Duty on Dumped Articles and for Determination of Injury) Rules, 1995.
- Following the review, the Designated Authority issued its final findings dated 25 June 2026, recommending modification of the quantum of ADD for the remaining period of the existing measure. The Central Government has now implemented those recommendations by substituting the earlier duty table.
Products Covered by the Revised ADD
The notification covers the following broad categories:
| Tariff Heading | Product |
| 5307 | Jute yarn/twine |
| 5310 | Hessian fabric / jute fabric including specified sacking cloth |
| 5607 | Jute yarn/twine falling within the notified product scope |
| 6305 | Jute sacking bags |
For purposes of the notification, the expression “jute products” includes jute yarn/twine (multiple folded/cabled and single), hessian fabric and jute sacking bags.
Revised ADD on Imports from Bangladesh
The notification introduces a detailed producer-specific duty structure for Bangladesh. Depending upon the producer and the type of jute product, the ADD ranges from Nil to USD 445 per metric tonne.
For example, the revised table provides:
| Product / category | Illustrative revised ADD |
| Jute yarn/twine – specified Bangladesh producers | Nil / USD 59 / 69 / 107 / 139 per MT, depending on producer |
| Hessian fabric – specified producers | Nil / USD 88 per MT, depending on producer |
| Jute sacking bags – specified producers | Nil / USD 94 / 120 / 155 per MT, depending on producer |
| Jute yarn/twine – other Bangladesh producers | USD 445 per MT |
| Hessian fabric – other Bangladesh producers | USD 88 per MT |
| Sacking bags – other Bangladesh producers | USD 283 per MT |
- The notification therefore does not impose a single uniform rate on all Bangladesh-origin jute goods. The applicable ADD depends upon the product, producer, country of origin and country of export.
- Several specified producers have received Nil ADD for particular product categories, while other named producers are subject to individual rates.
Revised ADD on Nepalese Jute Products
- A separate producer-specific structure has been prescribed for Nepal.
- For specified Nepalese producers, the notification provides rates including Nil, USD 32, USD 45, USD 56, USD 59, USD 60, USD 64, USD 94, USD 97, USD 132 and USD 153 per metric tonne, depending upon the producer and product concerned.
For Nepalese producers not individually specified in the relevant entries, the revised residual rates are:
| Product | ADD |
| Jute yarn/twine | USD 119 per MT |
| Hessian fabric | USD 292 per MT |
| Jute sacking bags | USD 247 per MT |
The same rates also appear in the corresponding entries dealing with specified origin/export combinations involving countries other than Bangladesh and Nepal.
Commercial Invoice Becomes Critical for Producer-Specific ADD
- An important compliance requirement has been incorporated for importers seeking the benefit of an individual producer-specific duty rate.
- The notification states that application of the specified individual rate is conditional upon submission to Customs of a valid commercial invoice containing a declaration dated and signed by an official of the entity issuing the invoice, along with that official’s name and designation.
- The declaration must essentially certify that the specified quantity of the relevant product sold for export to India was manufactured by the identified producer in the identified country and that the information contained in the invoice is complete and correct.
- Crucially, if such an invoice is not presented, the rate applicable to “all other producers” will apply.
- This makes producer identification and documentary accuracy particularly important for importers and Customs Brokers.
ADD Extended to Certain Jute Sacking Cloth from Bangladesh
- The amendment also substitutes paragraph 2 of the original notification.
- Under the revised provision, the ADD applicable to jute sacking bags originating in or exported from Bangladesh under the revised table will also apply to imports of “jute sacking cloth” falling under Heading 5310, originating in or exported from Bangladesh, except where it is produced by specified producers listed in the notification.
- The notification identifies ten producers for this purpose, including Mouna Jute Mills Limited, Arju Jute Mills Limited, Rahman Jute Mills (Pvt.) Limited, Jamuna Jute Industries Limited, Sagar Jute Spinning Mills Limited, Sidlaw Textiles (Bangladesh) Limited and others.
Conditional Relief for Jute Sacking Cloth Used for Other Purposes
- Importantly, ADD on jute sacking cloth under the substituted paragraph will not apply where prescribed conditions are satisfied.
- The notification requires that the goods be imported by a manufacturer other than a manufacturer of jute sacking bags and that the importer comply with the procedure prescribed under the Customs (Import of Goods at Concessional Rate of Duty or for Specified End Use) Rules, 2022.
- The importer must also furnish an undertaking to the jurisdictional Deputy Commissioner or Assistant Commissioner of Customs that the imported goods will be used for the intended purpose and will not be used for manufacturing jute sacking bags. If that condition is breached, the importer becomes liable to pay an amount equivalent to the ADD otherwise applicable under the notification.
- This effectively creates an end-use-based conditional exclusion from the ADD for qualifying imports of jute sacking cloth.
Legal Basis of the Amendment
- The Central Government has exercised its powers under Section 9A(1) and Section 9A(5) of the Customs Tariff Act, 1975, read with Rules 18 and 23 of the Anti-Dumping Rules, 1995, to amend the existing notification following the DGTR’s mid-term review.
- The notification does not create an entirely new anti-dumping measure. Instead, it revises the quantum and structure of the duty imposed under Notification No. 33/2022-Customs (ADD) for its remaining period following the mid-term review.
Key Compliance Takeaways for Importers
For Indian importers of jute products from Bangladesh and Nepal, determining ADD liability will now require a transaction-specific examination of the HS/tariff heading, precise product description, country of origin, country of export and actual producer.
Particular attention should be paid to the commercial invoice. Where an importer claims a lower or Nil producer-specific ADD, the prescribed manufacturer declaration becomes critical; failure to furnish the required invoice can result in application of the substantially higher “all other producers” rate.
Importers of jute sacking cloth under Heading 5310 should separately examine whether the expanded ADD provision applies and, where the cloth is imported for an eligible end-use other than manufacture of jute sacking bags, ensure strict compliance with the IGCR Rules, 2022 and the prescribed undertaking.
In case you face any issues related to Indirect Tax-Customs, GST, Foreign Trade Policy (FTP), Arbitration matters and Central Licensing and related advisory matters in India then please feel free to get in touch with SJ EXIM Services.
We offer Legal advice and litigation support in matters related to Indirect Tax-Customs, FTP, other Indirect Tax matters & Arbitration law, all sorts of Central licensing and related matters. Come and explore the new way of doing business with us!
We specialize in paralegal services, litigation support, tax and regulatory matters, delivering reliable, efficient, and result-oriented legal assistance.
Source: CBIC, Ministry of Finance, Govt. of India
Handy Download:
Connect with us for more-
@ Team S J EXIM SERVICES, New Delhi, IN
CP: Ms. Shubhra Jha, Founder
Tel: +91-11-4999 2707 I +91-9999005693
Web: www.sjexim.services
EMAIL: operations@sjexim.services I shubhra@sjexim.services
Facebook: www.facebook.com/sjeximservices
LinkedIn: https://www.linkedin.com/company/90794255/admin/feed/posts/
YouTube: https://www.youtube.com/@aadrikaalawindia
Subscribe our WhatsApp Channel: https://whatsapp.com/channel/0029VaTxDT8JZg4CHEOSoK47
Subscribe our Telegram Channel: https://t.me/sjeximindia


Leave a Reply