
“Indirect Tax I Indirect Tax Litigation I Customs & FTP I Central Licensing I Arbitration I Advisory”
Dated: 17.11.2026
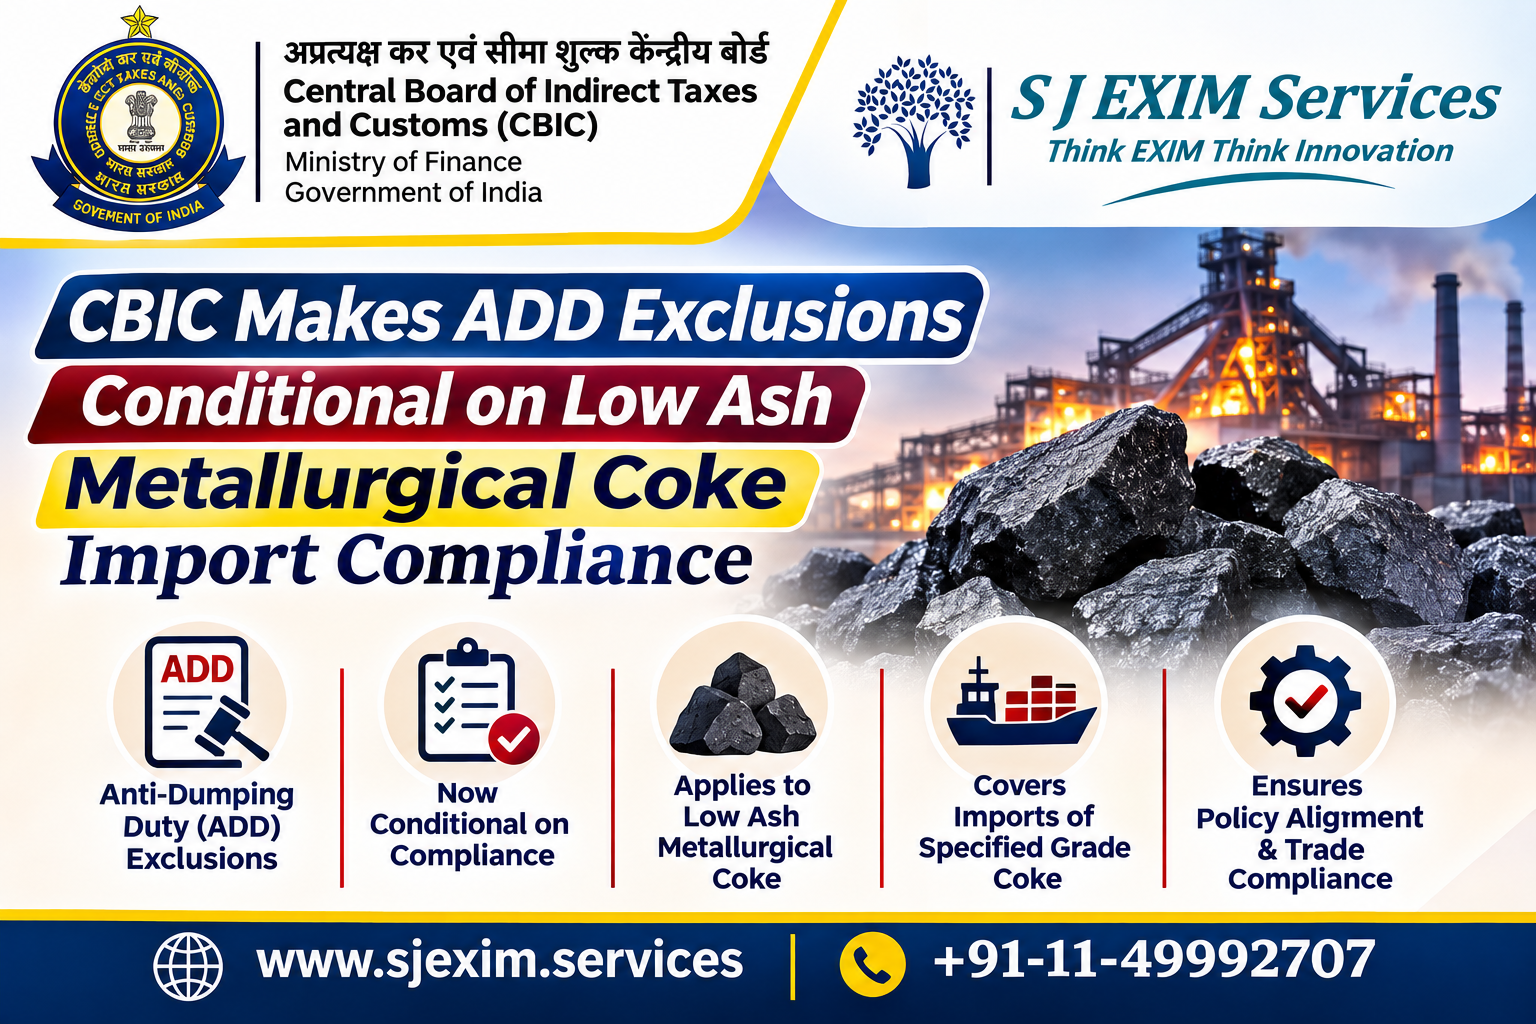
CBIC Makes ADD Exclusions Conditional on Low Ash Metallurgical Coke Import Compliance
Importers can claim the exclusions under clauses (a) and (c) of Notification No. 18/2026-Customs (ADD) only when they comply with the prescribed concessional-duty or end-use procedure.
The Government of India has issued Notification No. 28/2026-Customs (ADD), dated 13 November 2026, amending its earlier anti-dumping duty notification, No. 18/2026-Customs (ADD), dated 27 July 2026. The amendment makes procedural compliance a condition for obtaining specified duty exclusions.
What has changed
The amendment inserts a proviso in paragraph 2 of the original notification. It states that the exclusions listed in clauses (a) and (c) will apply only if the importer follows the Customs (Import of Goods at Concessional Rate of Duty or for Specified End Use) Rules, 2022.
In practical terms, eligibility for these exclusions is no longer determined solely by whether the imported goods fit within the relevant excluded categories. The importer must also meet the compliance requirements under the 2022 Rules.
Why the amendment matters
Anti-dumping duties are imposed to address injury caused by imported goods being sold at unfairly low prices. Exclusions from such duties can be available for particular goods or end uses, but this notification links those exclusions to a formal customs-control process.
This change strengthens the verification framework for excluded imports. It enables customs authorities to confirm that goods receiving the benefit are imported and used in line with the conditions applicable to concessional-duty or specified-end-use imports.
Impact on importers
Importers seeking the exclusions under clauses (a) or (c) should ensure that their import transactions comply with the procedural requirements of the 2022 Rules. A failure to follow that procedure may make the exclusions unavailable, resulting in anti-dumping duty becoming applicable.
Key compliance considerations include:
- Procedural eligibility: The importer must use the process prescribed for imports at a concessional rate of duty or for a specified end use.
- Documentation and declarations: Import records and customs filings should support the claimed exclusion and the intended qualifying use of the goods.
- End-use controls: Where the exclusion depends on a specified end use, the importer must be able to demonstrate compliance with the relevant conditions.
- Duty exposure: Non-compliance with the required procedure can jeopardize the exclusion even where the imported product would otherwise fall within clauses (a) or (c).
Legal basis and effective amendment
The Central Government issued the amendment under section 9A(1) and 9A(5) of the Customs Tariff Act, 1975, read with rules 18 and 20 of the Anti-dumping Duty Rules, 1995. The notification amends the principal anti-dumping duty notification issued on 27 July 2026.
The core policy outcome is clear: the specified anti-dumping duty exclusions are conditional benefits, and importers must follow the 2022 concessional-duty or end-use procedure to access them.
In case you face any issues related to Indirect Tax-Customs, GST, Foreign Trade Policy (FTP), Arbitration matters and Central Licensing and related advisory matters in India then please feel free to get in touch with SJ EXIM Services.
We offer Legal advice and litigation support in matters related to Indirect Tax-Customs, FTP, other Indirect Tax matters & Arbitration law, all sorts of Central licensing and related matters. Come and explore the new way of doing business with us!
We specialize in paralegal services, litigation support, tax and regulatory matters, delivering reliable, efficient, and result-oriented legal assistance.
Source: CBIC, Ministry of Finance, Govt. of India
Handy Download:
Connect with us for more-
@ Team S J EXIM SERVICES, New Delhi, IN
CP: Ms. Shubhra Jha, Founder
Tel: +91-11-4999 2707 I +91-9999005693
Web: www.sjexim.services
EMAIL: operations@sjexim.services I shubhra@sjexim.services
Facebook: www.facebook.com/sjeximservices
LinkedIn: https://www.linkedin.com/company/90794255/admin/feed/posts/
YouTube: https://youtube.com/@tradechaupaal
Subscribe our WhatsApp Channel: https://whatsapp.com/channel/0029VaTxDT8JZg4CHEOSoK47
Subscribe our Telegram Channel: https://t.me/sjeximindia



Leave a Reply