
“Indirect Tax I Indirect Tax Litigation I Customs & FTP I Central Licensing I Arbitration I Advisory”
Dated: 29.09.2026
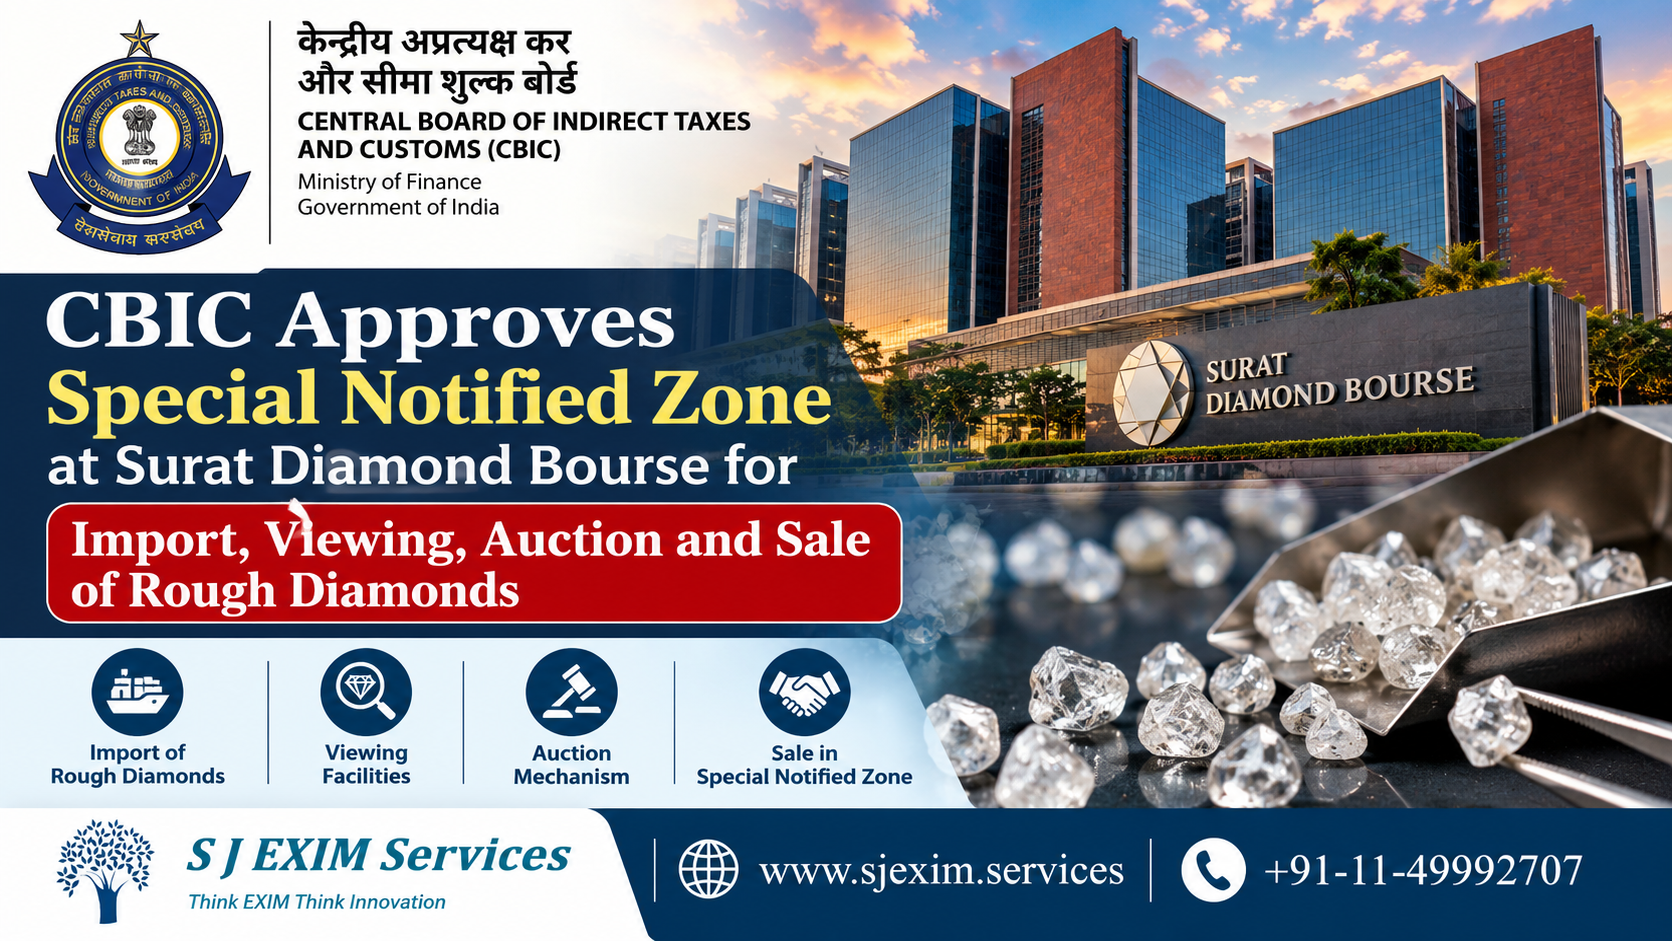
CBIC Approves Special Notified Zone at Surat Diamond Bourse for Import, Viewing, Auction and Sale of Rough Diamonds
The Central Board of Indirect Taxes & Customs (CBIC) has approved the establishment of a Special Notified Zone (SNZ) at the Surat International Diatrade Centre (SIDC), 2nd Floor, Tower-B, Surat Diamond Bourse, Dream City, Khajod, Surat, creating a Customs-supervised framework for eligible foreign diamond mining companies to bring rough diamonds into India for viewing, tendering, auction and sale to Indian diamond manufacturers and traders, with unsold lots being re-exported.
The decision has been communicated through Circular No. 44/2026-Customs dated 28 September 2026, issued by the Ministry of Finance, Department of Revenue, CBIC.
The Circular effectively provides for shifting the existing SNZ operated by SIDC from Gujarat Hira Bourse (GHB), Ichhapore, Surat, to the Surat Diamond Bourse premises at Khajod.
Why has the Special Notified Zone been shifted?
- The Gems & Jewellery Export Promotion Council (GJEPC), through its wholly owned subsidiary SIDC, was already operating an SNZ at Gujarat Hira Bourse, Ichhapore.
- That facility was intended to enable eligible foreign mining companies to consign rough diamonds to India for viewing and sale to Indian diamond manufacturers and traders, while permitting the re-export of unsold lots.
- GJEPC proposed shifting this facility to the 2nd Floor, Tower-B, Surat Diamond Bourse, Dream City, Khajod. The proposal was recommended by the Chief Commissioner of Customs, Gujarat Zone, Ahmedabad, based on the proposal furnished by the Commissioner of Customs, Ahmedabad.
Khajod is already a notified Customs location
An important regulatory foundation for the new SNZ already exists.
CBIC records that through Notification No. 74/2023-Customs (N.T.) dated 6 October 2023, as amended, Village Khajod, Taluka Majura, District Surat has already been notified under Section 7 of the Customs Act, 1962 for unloading imported goods and loading export goods in respect of specified commodities.
These include:
- diamonds;
- precious and semi-precious stones;
- pearls;
- jewellery made of gold or other precious metals, with or without studding;
- industrial diamonds, including powders, natural as well as synthetic; and
- synthetic stones. Circular-No-44-2026
The upper basement of the Surat Diamond Bourse building has also already been notified under Section 8 of the Customs Act, 1962 by the Commissioner of Customs, Ahmedabad.
Physical verification by Customs
- The Circular records that the proposed premises were physically inspected and verified by jurisdictional Customs officers.
- The layout plan was certified by a registered architect of the Surat Municipal Corporation and duly endorsed by jurisdictional Customs officers.
- Following this examination, CBIC decided to permit the Special Notified Zone facility at the new SIDC premises.
- However, the facility cannot commence operations merely by virtue of the Circular. SNZ operations can begin only after written authorisation from the Principal Commissioner or Commissioner of Customs, Ahmedabad.
Customs approval under Section 8
- SIDC is required to submit the floor plan and details of the proposed facilities, including security-related features, to the jurisdictional Customs authority.
- The Principal Commissioner or Commissioner of Customs, Ahmedabad may thereafter issue the necessary notification under Section 8 of the Customs Act, 1962 approving the proper place for unloading and loading the specified goods and defining the limits of the Customs area.
Custodian and Customs Cargo Service Provider
- The Circular further provides that SDB Diamond Bourse may be appointed as the Custodian/Customs Cargo Service Provider for the SNZ.
Such appointment is subject to compliance with:
Section 45 read with Section 141(2) of the Customs Act, 1962, and the Handling of Cargo in Customs Areas Regulations, 2009 (HCCAR).
- The necessary notification may be issued by the Commissioner of Customs, Ahmedabad.
- This means the new SNZ will operate as a closely controlled Customs area with defined responsibilities relating to custody, security, handling and accounting of the imported rough diamonds.
Who can consign rough diamonds to the SNZ?
The facility is not open indiscriminately to every overseas supplier.
- CBIC specifies that the companies entitled to consign rough diamonds to India for viewing and sale through the SNZ will be those permitted under RBI Circular No. 116 dated 1 April 2014, as amended from time to time.
- Accordingly, eligibility under the relevant RBI framework remains an important prerequisite.
Import permitted only through air cargo
CBIC has imposed a clear restriction on the mode of import:
Rough diamonds will be permitted to be imported through air cargo mode only.
- Imports through hand carriage or express courier service are expressly prohibited.
- This is an important operational compliance requirement for foreign mining companies, logistics operators and Indian participants dealing through the SNZ.
Mandatory documents for imported rough diamonds
Rough diamonds arriving in India for viewing, auction or sale must be accompanied by specified documentation, including:
- invoice containing declaration of value;
- packing list;
- insurance documents; and
- Kimberley Process Certificate, as provided in Circular No. 53/2003-Cus dated 23 June 2003.
The Kimberley Process documentation assumes particular significance in maintaining traceability and regulatory control over international trade in rough diamonds.
Customs movement from Mumbai to Surat
- Imported parcels intended for the SNZ will initially be transhipped from the Air Cargo Complex at Sahar, Mumbai, to Surat Diamond Bourse, Khajod, following the existing procedures and safeguards.
Upon arrival at Surat Diamond Bourse, the parcels will be examined by Customs in the presence of representatives of:
- the mining company;
- SIDC; and
- SDB Diamond Bourse as custodian.
Customs will tally the carat weight against the import invoice, packing list and Kimberley Certificate. The parcel will thereafter be sealed and transferred to the strong room within the SNZ.
This creates a controlled chain of custody from arrival in India through storage at the Special Notified Zone.
Access to the SNZ and security controls
The SNZ will be accessible to eligible traders for:
viewing of rough diamonds, auction, sale by bidding, and sale by negotiation.
- GJEPC/SDB Diamond Bourse will define eligibility conditions for visitors under intimation to Customs.
- Persons permitted to enter the SNZ must be issued photo identity cards, while SIDC and the custodian must maintain adequate security arrangements to prevent pilferage, damage or unauthorised removal of goods from the Customs area.
- The working hours and timings for viewing, auction and sale must also be determined in consultation with and with the approval of the jurisdictional Principal Commissioner/Commissioner of Customs.
No splitting or mixing of rough diamond lots
CBIC has prescribed important controls over the manner in which imported lots can be dealt with.
A viewing or auction process may result in:
- all imported lots being sold;
- only some lots being sold; or
- all lots remaining unsold.
A sale may involve a single lot or multiple lots, but sale of a sub-lot is prohibited.
- Further, mixing of different lots of rough diamonds during the viewing or sale process is not permitted.
- These controls are particularly important for maintaining traceability between the imported consignment, Customs documentation, Kimberley certification and the ultimate sale or re-export.
60-Day requirement for repacking after viewing or sale
- After completion of the viewing, auction or sale process, the rough diamonds must be repacked lot-wise in the same manner in which they were received, no later than 60 days from the date of import.
- The reconstituted parcels must be sealed in the presence of Customs, representatives of the mining company, SIDC and the custodian after the carat weight is reconciled with the import invoice, packing list and Kimberley Certificate.
Sale invoice becomes relevant Customs valuation document
- One of the most significant provisions of Circular No. 44/2026-Customs concerns valuation of rough diamonds successfully sold through the SNZ.
- CBIC provides that a successful auction, bidding process or negotiated sale will result in price discovery for the relevant lot or lots.
- The foreign diamond mining company will then issue a sale invoice for the lots sold.
Crucially:
- The sale invoice issued by the diamond mining company will constitute the relevant document for declaration of value under Section 14 of the Customs Act, 1962.
- This creates a direct connection between the price discovered through the SNZ transaction and Customs valuation for clearance of the sold diamonds.
Bill of Entry, duty payment and Out-of-Charge mandatory before removal
The Indian buyer purchasing a lot must file a Bill of Entry at Surat Diamond Bourse, Khajod.
The sold rough diamonds cannot be delivered or removed from the Customs area until:
- Customs assessment is completed;
- applicable Customs duty is paid; and
- the proper officer grants Out-of-Charge (OOC).
Thus, sale of a lot within the SNZ does not by itself permit its physical removal into the domestic market.
Unsold diamonds must be exported
- Rough diamonds that remain unsold are required to be exported.
- A Shipping Bill must be filed not later than 75 days from the date of import. Considering the anticipated regularity of these transactions, CBIC states that no separate permission for filing the Shipping Bill will be required.
- SDB Diamond Bourse, as custodian, will file the Shipping Bill “on A/C” of the consignor/mining company and the goods will be transhipped to the Air Cargo Complex at Sahar, Mumbai for shipment outside India.
- Importantly, the Circular states that unsold rough diamonds may be exported to any destination outside India.
- The Shipping Bill may use the IEC obtained by SDB Diamond Bourse, subject to conformity with the Foreign Trade Policy and RBI regulations.
Responsibility for custody and accounting
SIDC and SDB Diamond Bourse, as custodian, will be responsible for:
- receipt;
- sales;
- custody;
- delivery;
- re-export; and
- accounting
of rough diamonds imported for viewing and/or sale.
The records must be maintained in the form prescribed by the Principal Commissioner or Commissioner of Customs, Ahmedabad.
Transition from old SNZ to Surat Diamond Bourse
- CBIC has also provided a mechanism for orderly closure of the existing SNZ at Gujarat Hira Bourse, Ichhapore.
- Within 10 days of operationalisation of the new SNZ, the Principal Commissioner/Commissioner of Customs, Ahmedabad must initiate the de-notification process for closure of the old SNZ, which had earlier been covered by Circular No. 36/2019-Customs.
- Importantly, Customs has been directed to ensure uninterrupted functioning of the SNZ during the transition.
Compliance Matrix under Circular No. 44/2026-Customs
| Compliance Area | Requirement |
| New SNZ Location | SIDC, 2nd Floor, Tower-B, Surat Diamond Bourse, Khajod, Surat |
| Commencement | Only after written Customs authorisation |
| Customs Area | Approval/notification under Section 8 |
| Custodian | SDB Diamond Bourse may be appointed subject to Section 45, Section 141(2) and HCCAR 2009 |
| Eligible Foreign Companies | Companies permitted under RBI Circular No. 116 dated 01.04.2014, as amended |
| Import Mode | Air cargo only |
| Hand Carriage | Not permitted |
| Express Courier | Not permitted |
| Key Documents | Invoice, packing list, insurance documents and Kimberley Process Certificate |
| Initial Movement | Sahar Air Cargo Complex, Mumbai → Surat Diamond Bourse |
| Customs Verification | Carat weight reconciled with invoice, packing list and Kimberley Certificate |
| Sub-Lot Sale | Not permitted |
| Mixing of Lots | Not permitted |
| Repacking | Lot-wise, no later than 60 days from import |
| Valuation of Sold Lots | Sale invoice relevant for value declaration under Section 14 |
| Domestic Clearance | Bill of Entry + assessment + applicable duty + OOC |
| Unsold Goods | Shipping Bill to be filed within 75 days from import |
| Re-export Destination | Any destination outside India |
| Accounting Responsibility | SIDC and SDB Diamond Bourse |
| Old SNZ | De-notification process to begin within 10 days of new SNZ becoming operational |
Customs Act provisions expressly involved
The Circular directly engages several important provisions of the Customs Act, 1962:
- Section 7 – notification of places for unloading imported goods and loading export goods.
- Section 8 – approval of proper places for loading/unloading and specification of the limits of a Customs area.
- Section 14 – valuation of imported goods; the sale invoice following price discovery at the SNZ will be the relevant document for declaration of value.
- Section 45 – custody and removal of imported goods in a Customs area.
- Section 141(2) – regulatory framework governing receipt, storage, delivery, dispatch and handling of imported/export goods in Customs areas.
Why Circular No. 44/2026-Customs is significant
- The Circular establishes a detailed Customs-controlled mechanism through which eligible overseas diamond mining companies can bring rough diamonds into India without the commercial transaction necessarily being completed before arrival.
- The imported lots can first be viewed and offered through auction, bidding or negotiation within the SNZ. Where a transaction succeeds, the resulting sale invoice becomes relevant for declaring Customs value under Section 14, followed by filing of the Bill of Entry, assessment, payment of applicable duty and OOC.
- Where a lot remains unsold, it can instead be re-exported in accordance with the prescribed procedure.
- For India’s diamond trade, the framework therefore creates a regulated interface between foreign mining companies, Indian diamond manufacturers/traders, Customs, GJEPC, SIDC and Surat Diamond Bourse, while maintaining documentary traceability and Customs control over the imported goods throughout the process.
Key takeaway
Circular No. 44/2026-Customs marks the relocation and establishment of the Special Notified Zone at Surat Diamond Bourse, Khajod, for eligible foreign mining companies to bring rough diamonds into India for viewing, auction and negotiated sale.
The new facility, however, remains subject to written operational authorisation by jurisdictional Customs and strict controls over air-cargo import, Kimberley Process documentation, Customs examination, custody, lot integrity, valuation, Bill of Entry filing, duty payment, Out-of-Charge and re-export of unsold diamonds.
In case you face any issues related to Indirect Tax-Customs, GST, Foreign Trade Policy (FTP), Arbitration matters and Central Licensing and related advisory matters in India then please feel free to get in touch with SJ EXIM Services.
We offer Legal advice and litigation support in matters related to Indirect Tax-Customs, FTP, other Indirect Tax matters & Arbitration law, all sorts of Central licensing and related matters. Come and explore the new way of doing business with us!
We specialize in paralegal services, litigation support, tax and regulatory matters, delivering reliable, efficient, and result-oriented legal assistance.
Source: CBIC, Ministry of Finance, Govt. of India
Handy Download:
Connect with us for more-
@ Team S J EXIM SERVICES, New Delhi, IN
CP: Ms. Shubhra Jha, Founder
Tel: +91-11-4999 2707 I +91-9999005693
Web: www.sjexim.services
EMAIL: operations@sjexim.services I shubhra@sjexim.services
Facebook: www.facebook.com/sjeximservices
LinkedIn: https://www.linkedin.com/company/90794255/admin/feed/posts/
YouTube: https://www.youtube.com/@aadrikaalawindia
Subscribe our WhatsApp Channel: https://whatsapp.com/channel/0029VaTxDT8JZg4CHEOSoK47
Subscribe our Telegram Channel: https://t.me/sjeximindia




Leave a Reply