
“Indirect Tax I Indirect Tax Litigation I Customs & FTP I Central Licensing I Arbitration I Advisory”
Dated: 08.10.2026
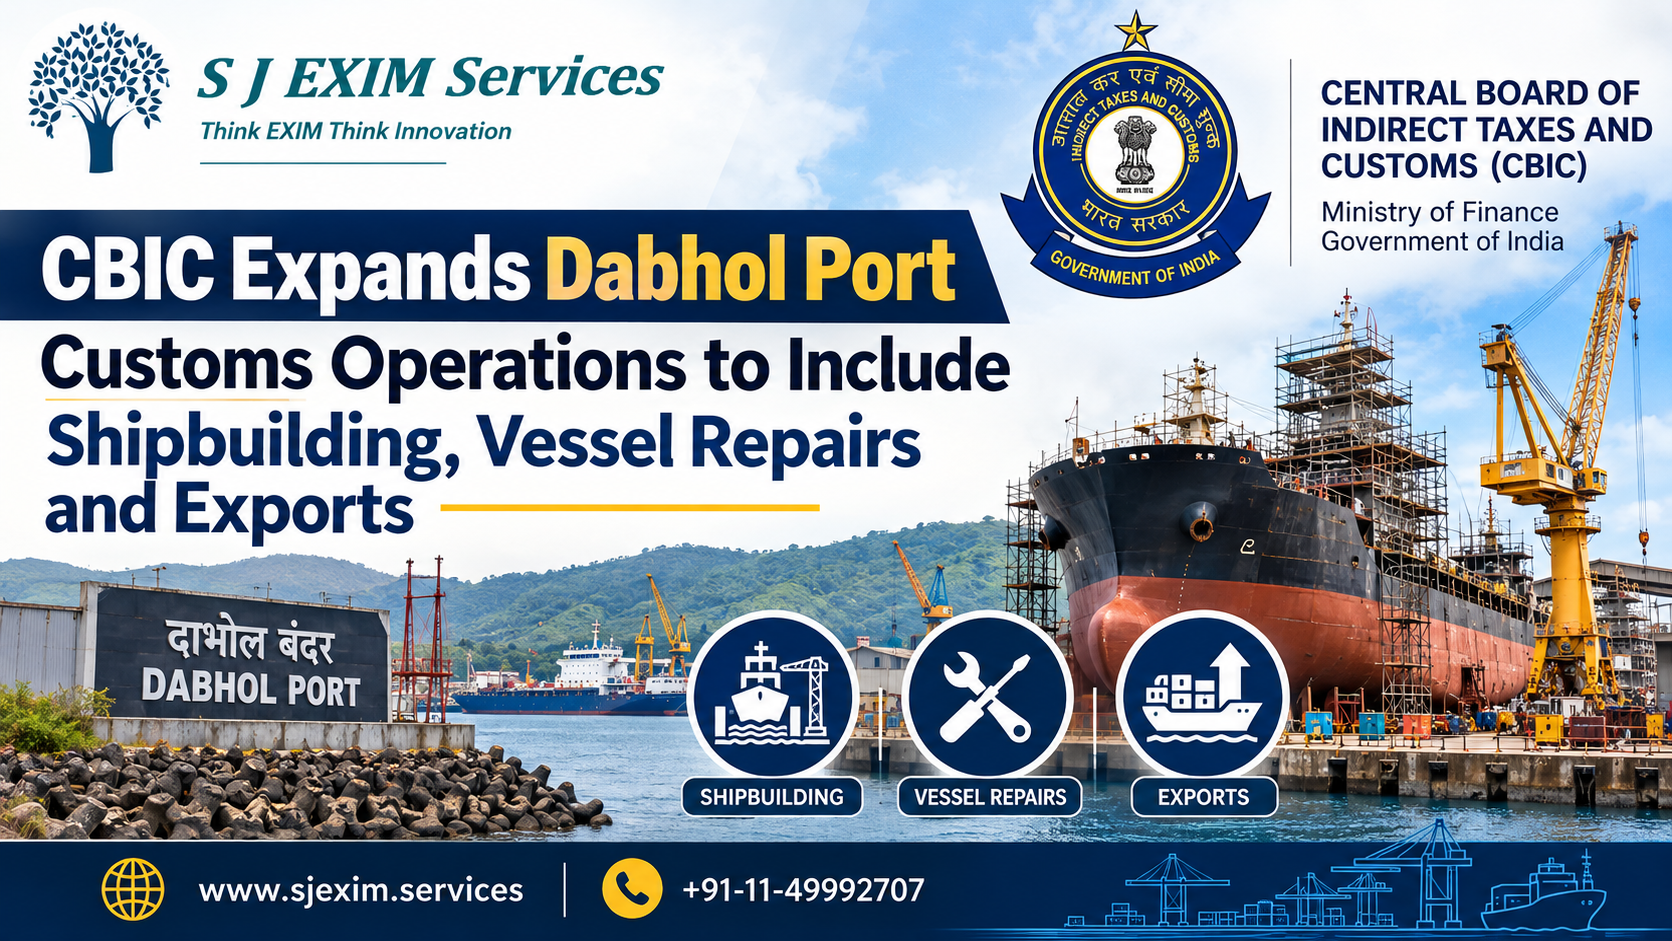
CBIC Expands Dabhol Port Customs Operations to Include Shipbuilding, Vessel Repairs and Exports
The Central Board of Indirect Taxes and Customs (CBIC), Ministry of Finance, has issued Notification No. 81/2026-Customs (N.T.), dated 7 October 2026, amending Notification No. 62/1994-Customs (N.T.) to revise the specified customs operations permitted at Dabhol Port in Maharashtra.
Issued under Section 7(1)(a) of the Customs Act, 1962, the notification substitutes the existing entries relating to Dabhol Port and expressly includes specified activities concerning the manufacture, repair, import and export of ships, barges, similar vessels and rigs by M/s Square Port Shipyard Private Limited.
The amendment is significant for the shipping, shipbuilding, maritime engineering and port logistics sectors, particularly in relation to the customs treatment and operational handling of vessels and materials intended for shipbuilding and repair activities.
Background: Customs Port Notifications Under Section 7 of the Customs Act, 1962
- Section 7(1)(a) of the Customs Act, 1962 empowers the CBIC to appoint customs ports and specify the purposes for which goods may be loaded or unloaded at such ports.
- Notification No. 62/1994-Customs (N.T.), dated 21 November 1994, is one of the principal notifications identifying customs ports and the purposes for which they are authorised to undertake specified import and export operations.
- Through Notification No. 81/2026-Customs (N.T.), CBIC has amended the entry at Serial No. 8 relating to Maharashtra, specifically replacing Item (1) concerning Dabhol Port and its corresponding authorised operations.
- The amendment does not constitute an unrestricted authorisation for all categories of import and export cargo. Rather, it specifies the activities for which Dabhol Port is authorised under the amended notification.
Revised Customs Operations Permitted at Dabhol Port
The amended notification identifies six categories of activities.
1. Unloading of Machinery and Equipment for Ratnagiri Power Project
- Dabhol Port continues to be authorised for unloading machinery and equipment intended for the Ratnagiri Gas and Power Private Limited Power Project.
- This provision supports the handling of project-related capital equipment and machinery through the designated port.
2. Unloading of Liquefied Natural Gas and Naphtha
- The notification expressly permits the unloading of liquefied natural gas (LNG) and naphtha at Dabhol Port.
- These commodities are associated with energy infrastructure and industrial operations, and their inclusion maintains the port’s specified role in handling such cargo.
3. Loading of Imported Project Machinery for Export
- The amended entry permits the loading, for export, of imported machinery and equipment originally imported for the Ratnagiri Gas and Power Private Limited Power Project.
- This provision is relevant where project-related machinery or equipment is proposed to be exported from India.
- However, the notification itself does not prescribe any independent exemption from customs duty or establish automatic eligibility for duty drawback or re-export benefits. Such matters remain subject to the applicable statutory provisions and notifications.
4. Unloading of Goods for Shipbuilding and Vessel Repairs
An important inclusion under the revised notification is the authorisation for:
Unloading of goods for the manufacture and repairs of ships, barges, similar vessels and rigs by M/s Square Port Shipyard Private Limited.
- This provision expressly recognises the handling of goods intended for specified shipbuilding and repair activities at Dabhol Port.
- It may facilitate the movement of machinery, equipment, components and other materials required for such operations, subject to applicable customs requirements.
5. Import of Ships, Barges, Vessels and Rigs for Repairs
- The notification additionally authorises the import of ships, barges, similar vessels and rigs by M/s Square Port Shipyard Private Limited for repair purposes.
- This provision is particularly relevant to the maritime repair industry, where vessels may enter India for maintenance, refurbishment, repairs or related technical work.
- Importers and shipyard operators must nevertheless examine the applicable customs procedures, tariff classification, valuation, duty liability and any relevant exemption or re-export conditions.
6. Export of Ships, Barges, Similar Vessels and Rigs
- The notification also authorises the export by M/s Square Port Shipyard Private Limited of ships, barges, similar vessels and rigs.
- This creates an express customs-port authorisation for the specified export activities.
- The actual export process will continue to be governed by the Customs Act, 1962, applicable export documentation requirements and other relevant regulatory provisions.
Legal Significance of Notification No. 81/2026-Customs (N.T.)
The notification carries several important legal and operational implications.
- First, it expands the expressly specified scope of customs operations at Dabhol Port. By including shipbuilding, vessel repair and related import-export activities, CBIC has provided statutory recognition for these particular operations at the port.
- Second, it identifies the authorised operator for the additional shipyard-related activities. Clauses (d), (e) and (f) specifically name M/s Square Port Shipyard Private Limited. Accordingly, the amendment should not be interpreted as automatically extending identical permissions to every shipyard or maritime operator.
- Third, the amendment concerns customs-port authorisation rather than substantive duty exemption. Appointment or specification of a customs port under Section 7 does not, by itself, exempt goods from customs duty or dispense with the requirements of assessment, clearance, import-export declarations and allied regulatory approvals.
- Fourth, the notification may have implications for maritime project planning. Operators undertaking vessel repairs, shipbuilding and related activities must align their cargo-handling arrangements with the precise scope of the customs-port notification and applicable permissions.
Compliance Considerations for Importers, Exporters and Shipyard Operators
Businesses proposing to undertake activities through Dabhol Port should carefully evaluate the following:
- Scope of port authorisation: Verify whether the proposed cargo and activity fall within the purposes specified under the amended notification.
- Identity of the authorised operator: Examine the specific reference to M/s Square Port Shipyard Private Limited for shipbuilding and repair-related operations.
- Customs classification and valuation: Determine the applicable tariff classification and assessable value of imported vessels, machinery, equipment and components.
- Import and export documentation: Ensure appropriate filing of Bills of Entry, Shipping Bills and supporting documentation, as applicable.
- Temporary importation and re-export: Where vessels are imported for repairs and subsequently exported, examine the applicable legal provisions and conditional exemptions, if any.
- Allied regulatory compliance: Assess whether approvals or requirements under DGFT, port, maritime, environmental or other applicable laws are relevant.
These considerations are particularly important because the notification authorises specified port operations but does not independently resolve all associated customs and regulatory obligations.
Impact on India’s Shipbuilding and Maritime Industry
- The inclusion of shipbuilding and vessel repair activities within the specified customs operations at Dabhol Port is a relevant regulatory development for India’s maritime sector.
- The revised authorisation may support the movement of vessels, shipbuilding materials and repair-related cargo through Dabhol Port for the identified operator.
- It may also provide greater operational clarity for planning import, repair and export transactions involving ships, barges, similar vessels and rigs.
- However, the practical benefits will depend on port infrastructure, customs procedures, applicable approvals and the commercial arrangements governing individual transactions.
Conclusion
CBIC Notification No. 81/2026-Customs (N.T.), dated 7 October 2026, marks a significant amendment to the customs-port authorisation applicable to Dabhol Port, Maharashtra.
By expressly including the unloading of shipbuilding and repair-related goods, the import of vessels for repairs and the export of vessels by M/s Square Port Shipyard Private Limited, the notification broadens the specified purposes for which Dabhol Port may undertake customs operations.
For maritime businesses, shipyards, importers and exporters, the amendment underscores the importance of examining port-specific customs authorisations alongside the broader requirements of the Customs Act, 1962 and allied regulations.
In case you face any issues related to Indirect Tax-Customs, GST, Foreign Trade Policy (FTP), Arbitration matters and Central Licensing and related advisory matters in India then please feel free to get in touch with SJ EXIM Services.
We offer Legal advice and litigation support in matters related to Indirect Tax-Customs, FTP, other Indirect Tax matters & Arbitration law, all sorts of Central licensing and related matters. Come and explore the new way of doing business with us!
We specialize in paralegal services, litigation support, tax and regulatory matters, delivering reliable, efficient, and result-oriented legal assistance.
Source: CBIC, Ministry of Finance, Govt. of India
Handy Download:
Connect with us for more-
@ Team S J EXIM SERVICES, New Delhi, IN
CP: Ms. Shubhra Jha, Founder
Tel: +91-11-4999 2707 I +91-9999005693
Web: www.sjexim.services
EMAIL: operations@sjexim.services I shubhra@sjexim.services
Facebook: www.facebook.com/sjeximservices
LinkedIn: https://www.linkedin.com/company/90794255/admin/feed/posts/
YouTube: https://www.youtube.com/@aadrikaalawindia
Subscribe our WhatsApp Channel: https://whatsapp.com/channel/0029VaTxDT8JZg4CHEOSoK47
Subscribe our Telegram Channel: https://t.me/sjeximindia



Leave a Reply