
“Indirect Tax I Indirect Tax Litigation I Customs & FTP I Central Licensing I Arbitration I Advisory”
Dated: 10.10.2026
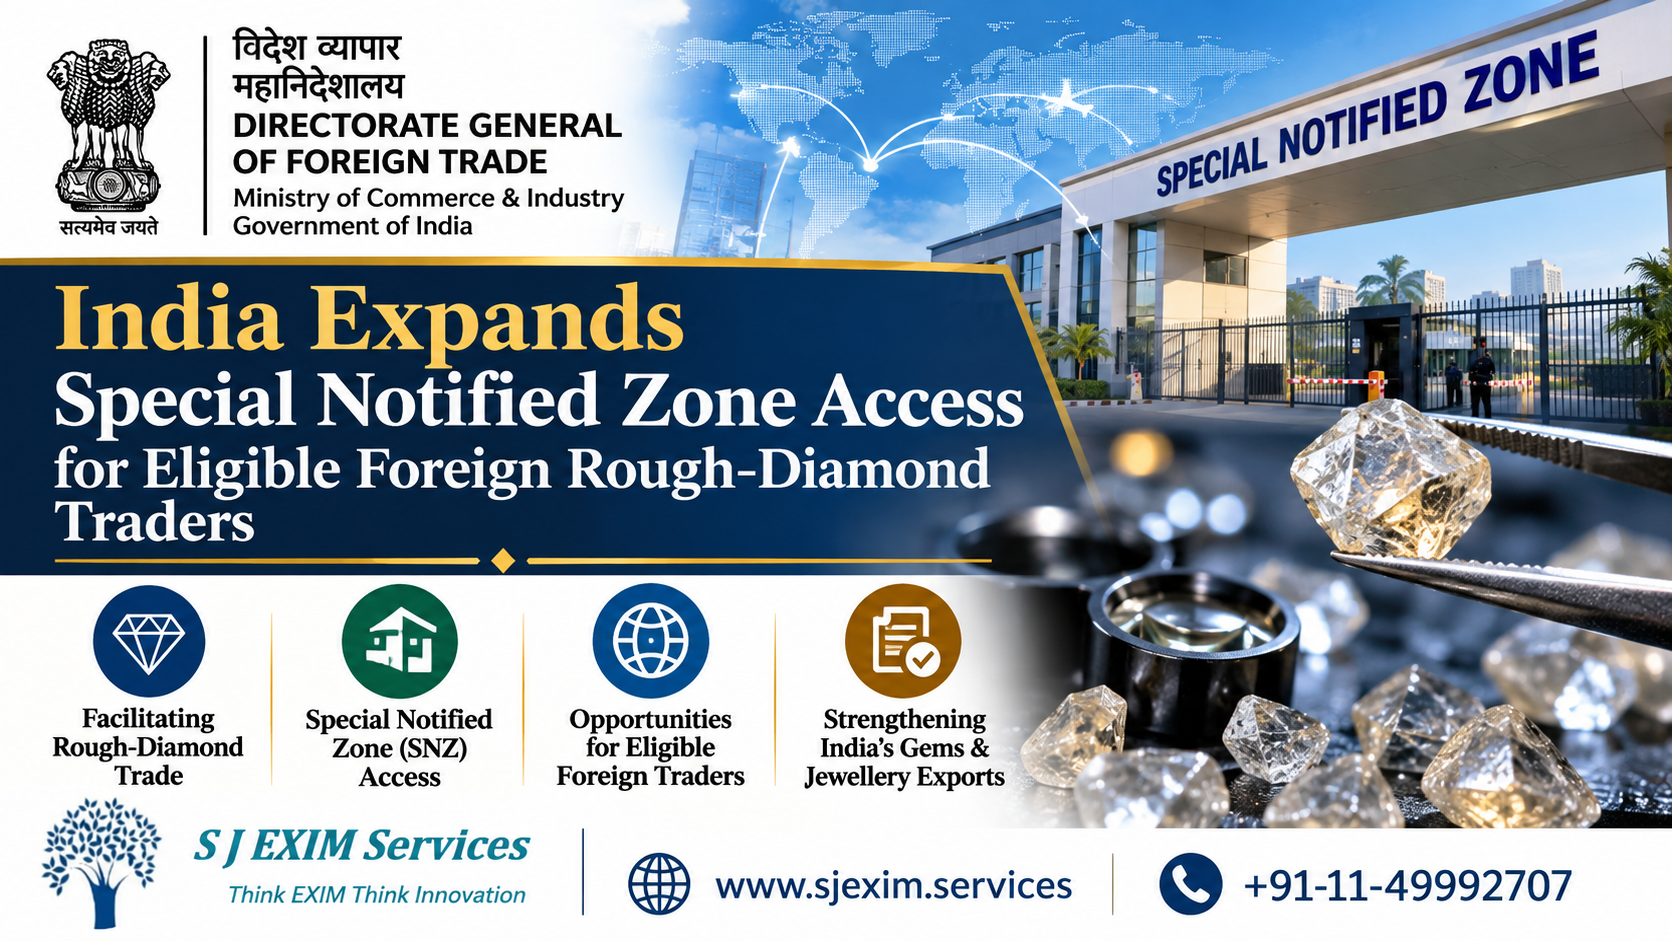
India Expands Special Notified Zone Access for Eligible Foreign Rough-Diamond Traders
India has amended its Foreign Trade Policy to allow specified foreign entities to import, auction, sell and re-export rough diamonds through Special Notified Zones (SNZs), subject to Customs supervision and CBIC procedures.
A targeted change to the rough-diamond trading framework
The Directorate General of Foreign Trade (DGFT), under the Ministry of Commerce & Industry, has revised Paragraph 4.49 of the Foreign Trade Policy (FTP) 2023 with immediate effect. The amendment expands the category of participants permitted to conduct rough-diamond transactions in India’s Special Notified Zones.
Previously, the policy allowed import, auction or sale, and re-export of rough diamonds in an SNZ on a consignment or outright basis, subject to operation by the SNZ operator and Customs supervision. The revised provision expressly extends these permissions to eligible foreign entities.
The policy change is intended to provide a clearer legal and operational basis for qualifying overseas participants to use India’s regulated SNZ infrastructure for rough-diamond trade.
Activities now permitted in Special Notified Zones
Under the revised Paragraph 4.49, eligible foreign entities may undertake the following activities in an SNZ:
- Import rough diamonds into the Special Notified Zone.
- Auction rough diamonds within the SNZ.
- Sell rough diamonds within the SNZ.
- Re-export unsold rough diamonds from the SNZ.
These activities may be conducted on either a consignment basis or an outright basis. This gives eligible participants flexibility in structuring transactions, while keeping trade activity within a defined and supervised regulatory environment.
Which foreign entities are eligible?
The amendment identifies eligible foreign entities by reference to Entry 13F of Schedule IV of the Income-tax Act, 2025, subject to the conditions applicable under that provision.
The eligible categories include:
- Foreign companies engaged in diamond mining
- Sightholders of diamond-mining companies
- Brokers connected with the sale of rough diamonds
- Aggregators connected with the sale of rough diamonds
- Tender entities involved in rough-diamond sales
- Auction entities involved in rough-diamond sales
By explicitly naming these categories, the amendment recognizes the range of participants involved in the international rough-diamond supply chain, from mining companies and their approved buyers to intermediaries and auction organizers.
Regulatory safeguards remain in place
The expanded access does not remove regulatory oversight. Rough-diamond transactions under this framework must take place in a Special Notified Zone that is administered by the relevant SNZ operator and remains under the supervision of Customs.
In addition, the Central Board of Indirect Taxes and Customs (CBIC) will continue to prescribe the procedures governing:
- Import of rough diamonds
- Auction and sale within the SNZ
- Re-export of unsold rough diamonds
This means that eligible foreign entities can access the SNZ framework only in accordance with the applicable CBIC procedures and the conditions linked to their eligibility under the Income-tax Act, 2025.
Why the amendment matters
The revised policy provides greater certainty for qualifying overseas companies and market participants seeking to conduct rough-diamond transactions in India. It formally acknowledges that foreign miners, sightholders, brokers, aggregators, and tender or auction entities may use SNZs for permitted activities.
The amendment may strengthen India’s position in the global diamond ecosystem in several ways:
- Broader market participation: Eligible foreign entities can conduct authorized trading activities through India’s SNZ framework.
- Structured transaction environment: Auctions, sales and re-exports occur within a designated zone administered by an operator and supervised by Customs.
- Operational flexibility: Consignment and outright transaction models are both permitted.
- Regulatory clarity: Eligibility criteria and CBIC procedures establish clearer compliance boundaries for international participants.
Compliance considerations for participants
Entities intending to use this route should ensure that they fall within an eligible category covered by Entry 13F of Schedule IV of the Income-tax Act, 2025, and satisfy the applicable conditions under that entry.
They must also comply with the CBIC procedures in force for importing, auctioning, selling and re-exporting rough diamonds. In particular, re-export permissions apply to rough diamonds that remain unsold, and all activity must be carried out through the SNZ under Customs supervision.
Immediate effect
The amendment to Paragraph 4.49 of FTP 2023 takes effect immediately. It was issued by the Central Government under the Foreign Trade (Development and Regulation) Act, 1992, with the approval of the Minister of Commerce & Industry. Overall, the notification creates an express pathway for eligible foreign rough-diamond market participants to use India’s Special Notified Zones for import, trading and re-export activities, while preserving Customs control and CBIC-led procedural requirements.
In case you face any issues related to Indirect Tax-Customs, GST, Foreign Trade Policy (FTP), Arbitration matters and Central Licensing and related advisory matters in India then please feel free to get in touch with SJ EXIM Services.
We offer Legal advice and litigation support in matters related to Indirect Tax-Customs, FTP, other Indirect Tax matters & Arbitration law, all sorts of Central licensing and related matters. Come and explore the new way of doing business with us!
We specialize in paralegal services, litigation support, tax and regulatory matters, delivering reliable, efficient, and result-oriented legal assistance.
Source: DGFT
Handy Download:
Connect with us for more-
@ Team S J EXIM SERVICES, New Delhi, IN
CP: Ms. Shubhra Jha, Founder
Tel: +91-11-4999 2707 I +91-9999005693
Web: www.sjexim.services
EMAIL: operations@sjexim.services I shubhra@sjexim.services
Facebook: www.facebook.com/sjeximservices
LinkedIn: https://www.linkedin.com/company/90794255/admin/feed/posts/
YouTube: https://www.youtube.com/@aadrikaalawindia
Subscribe our WhatsApp Channel: https://whatsapp.com/channel/0029VaTxDT8JZg4CHEOSoK47
Subscribe our Telegram Channel: https://t.me/sjeximindia



Leave a Reply